
Free 15-minute credit review
Medical debt on your credit? Know what’s really there before you pay.
Some medical bills shouldn’t be on your report at all — and others are reported incorrectly. A real specialist helps you see what’s actually there before you pay or settle.
No credit card · no obligation · phone optional · your info is never sold.
Medical Debt Report Scan
Illustrative example — not a real credit report.
Prefer to see your own credit first? See my scores & report →
Find out what’s actually reporting — before you pay
Medical billing is messy — bills get duplicated, balances go stale, and some collections shouldn’t be on your report at all. Paying the wrong thing won’t always help. Fifteen minutes tells you what’s really there.
The FTC found 1 in 5 consumers had an error on at least one of their credit reports — and medical collections are a common source. What’s reported may not be the whole story.
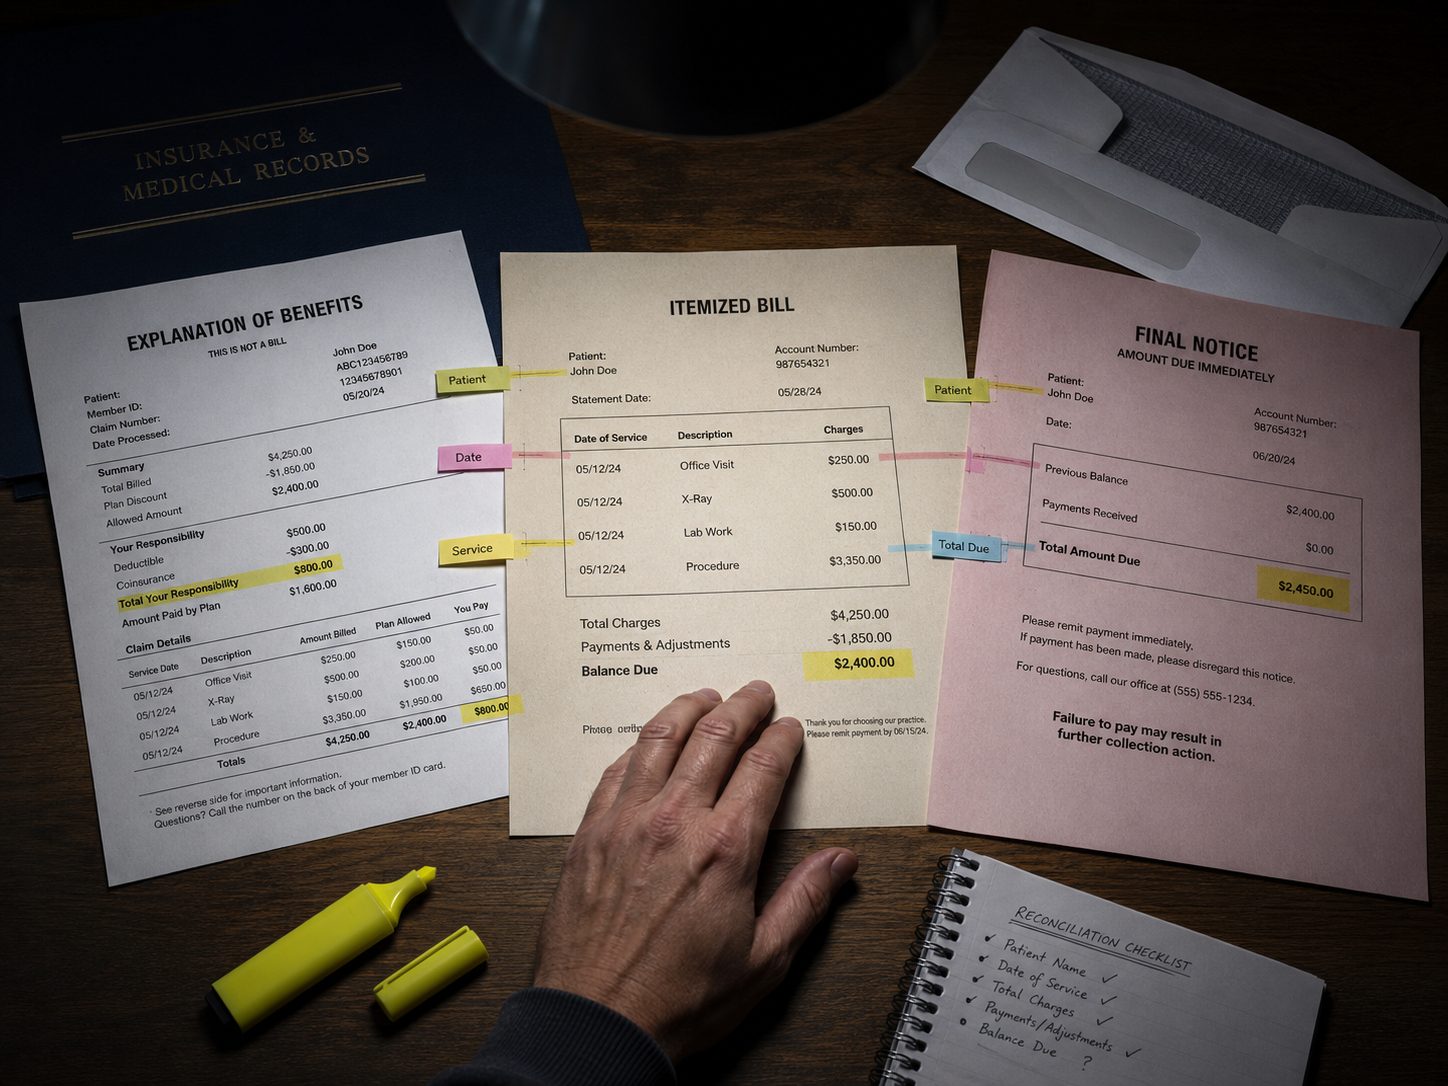
Make three records tell the same story
Before you pay or negotiate a medical collection, put these three side by side. The numbers should add up — when they don’t, find the mismatch first.
Tip: the EOB is not a bill. Compare the provider, service date, insurance adjustments, your responsibility, and any payments already made.
How to read an Explanation of Benefits (CMS). Medical-debt reporting rules vary — confirm before you act.
What may not belong on your report
Medical debt follows different rules than other debt, and those rules have shifted — so what’s allowed to report can vary. Before you act, it’s worth confirming what’s actually there.
The good news: once you can see what’s actually on the report, each item becomes something you can understand and act on — that’s the whole point of the free review.
You’ll talk to an actual credit specialist
No call-center script, no upsell ambush. A specialist at MSI Credit Solutions goes through your report with you, helps you see what medical items are actually reporting, and gives you a straight read before you pay or settle.
It’s free, takes about 15 minutes, and there’s no obligation to do anything afterward.
Start my free reviewWhat you’ll know after the free review
No pressure, no jargon — just a straight answer and a plan.
Tell us what happened
A quick 15-minute call. Share what you’re dealing with — and we look at what’s actually on your credit report.
We pinpoint what may be hurting you
We go through the specific items on a report that can cause trouble — and flag what may apply to you.
You leave with a realistic plan
A clear, honest action plan: what may be disputable, what to rebuild, and a realistic sense of timing.
We can’t guarantee approvals or a specific score increase, and we can’t remove accurate information. What we can do is show you what’s affecting your credit, what may be disputable, and exactly what to do next.
What you’ll walk away with
- What medical items are actually on your report
- Which may be inaccurate, duplicated, or outdated
- What may be disputable — before you pay or settle
- A realistic next-step plan for the medical debt
Backed by MSI Credit Solutions
Questions people ask
Do medical bills affect your credit score?
They can, but the rules have shifted and vary. Paid medical collections and many smaller balances have been removed from credit reports under recent industry changes, and reporting rules differ by bureau and state. Before you pay, it’s worth confirming what’s actually reporting.
How do I get medical bills off my credit report?
If a medical collection is inaccurate, duplicated, already paid, or shouldn’t be reporting under current rules, it may be disputable with the bureaus. We can’t promise removal of accurate items, but a review helps you see what may not belong.
Should I pay a medical collection on my credit report?
Not before you check it. Medical billing is error-prone — bills get duplicated, balances go stale, and some collections shouldn’t be there. Paying the wrong thing won’t always help, so confirm what’s actually owed first.
How long does medical debt stay on your credit report?
It varies with current reporting rules and the type of debt. Rather than rely on a single number, it’s best to verify what’s reporting on your specific report and whether it’s being reported correctly.
Know what’s really on your report — free
A 15-minute review helps you see what medical debt is actually reporting, what may be disputable, and what to do before you pay or settle — no credit card, no obligation.
Get my free medical-debt reviewFree · about 15 minutes · phone optional · no credit card · your info is never sold.