Prequalify vs. Apply: Shopping for a Loan Without Hurting Your Credit
You can shop for a loan and compare real offers without denting your credit — if you understand the difference between prequalifying and applying.
Loan shopping has a built-in trap: every formal application can add a hard inquiry, so comparing several lenders the wrong way can chip at your score. The good news is there’s a low-risk way to shop — prequalification — if you know how it differs from applying.
Here’s the distinction, and how to use it.
Prequalification uses a soft pull
Prequalifying (or pre-approval, as some lenders call it) usually involves a soft inquiry — the lender takes a light look at your credit to estimate whether you’d be approved and on what terms. A soft pull doesn’t affect your score, so you can prequalify with several lenders freely.
Applying uses a hard pull
A formal application triggers a hard inquiry, which can lower your score slightly and temporarily. One is no big deal; several unrelated applications in a short span add up and can signal risk. So you want to reserve the hard pull for when you’re ready to actually take a loan.
What “prequalified” actually means
Important caveat: prequalification is an estimate, not a guarantee. It’s based on limited information, and the final terms can change once you formally apply and the lender verifies everything. Treat a prequalified offer as a strong indication and a comparison tool — not a done deal.
Rate-shopping windows
Even when you do apply, scoring models give you room to shop certain loans. For auto, mortgage, and student loans, multiple hard inquiries of the same type within a focused window — often 14 to 45 days — are counted as a single inquiry. Personal loans don’t always get the same treatment, which is exactly why prequalifying first matters there.
How to compare offers safely
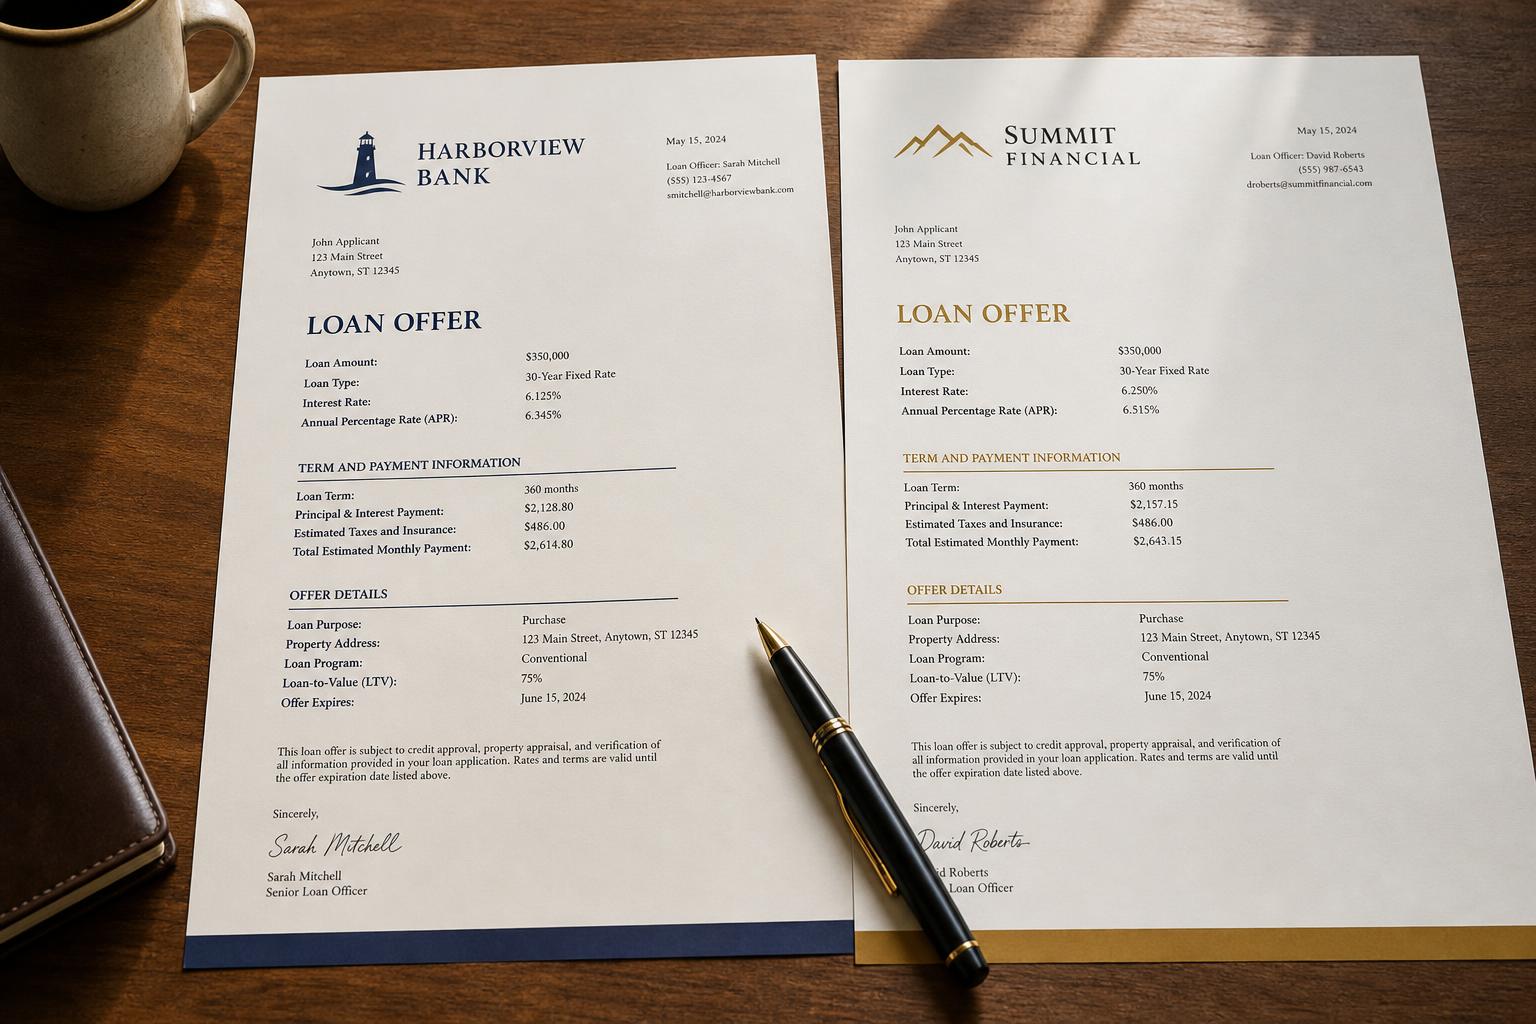
The safe sequence: prequalify with several lenders using soft pulls, compare the estimated rates, terms, and fees, then formally apply to the one you choose. That way you do your comparison shopping without hard inquiries and spend your single hard pull only when you’ve picked a winner.
When to formally apply
Apply once you’ve compared offers and are ready to move forward — ideally when your credit is in good shape, so you qualify for the best terms. If a previous application was declined, make sure you’ve addressed the reasons first (see why you were denied a personal loan) before adding another inquiry.
Key takeaways
- Prequalifying uses a soft pull and doesn’t affect your score — shop freely.
- A formal application uses a hard pull that can dip your score slightly and temporarily.
- Prequalified means “likely,” not guaranteed — final terms can change.
- Auto, mortgage, and student-loan inquiries within ~14–45 days count as one; personal loans may not.
- Prequalify with several lenders, compare, then apply to just the one you choose.
Shopping for a loan?
A free 15-minute review shows what lenders will see on your credit report — so you can prequalify and apply from a position of strength. No obligation.
Free · about 15 minutes · no credit card · no obligation.
Sources: Consumer Financial Protection Bureau (CFPB) — prequalification vs. preapproval, hard vs. soft inquiries, and rate shopping; FICO — rate-shopping inquiry windows. Practices vary by lender and loan type; this is general education, not financial advice.